 Log In
 Register


 Topic RSS

 Facebook
 Twitter
 Email this
7:58 pm
May 15, 2007
 Offline


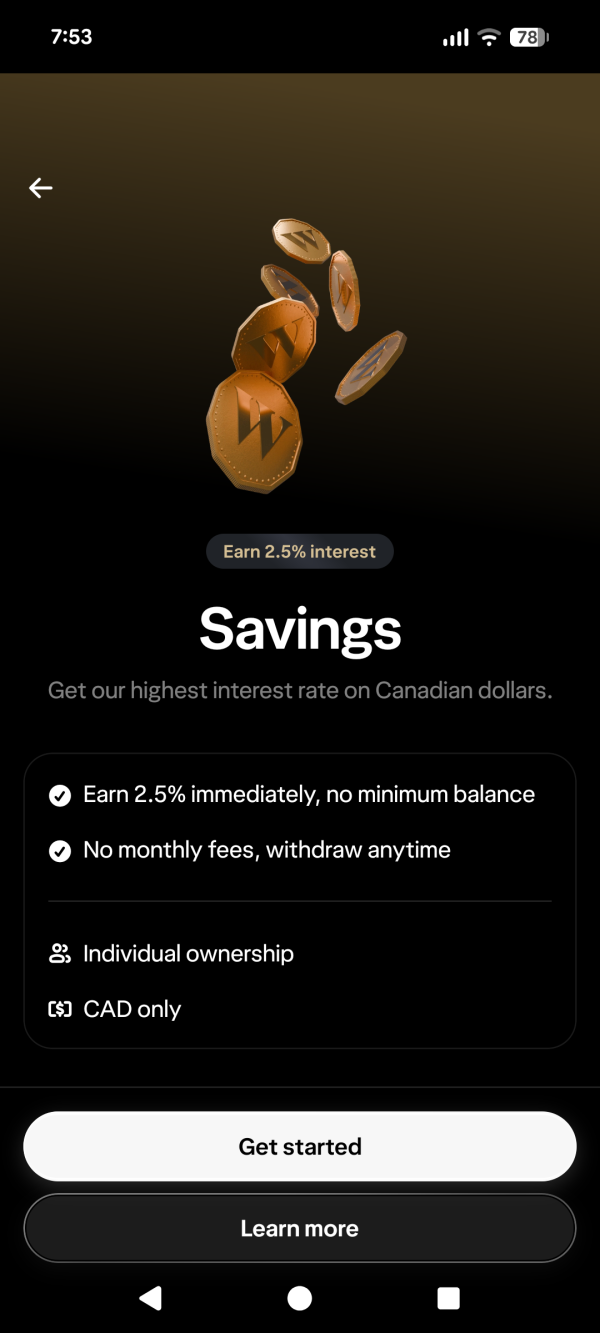
Looks like a new Wealthsimple savings account has shown up.
No joint accounts, CIPF coverage (not CDIC), 2.50% regardless of direct deposit or status, limited features as you have to transfer it to the chequing account to move the money out.
8:16 pm
June 22, 2023
Offline

https://help.wealthsimple.com/.....count-beta
I saw this on Reddit and it seems reasonably important to share at this time.
1:00 pm
June 22, 2023
Offline
https://help.wealthsimple.com/.....gs-account
That was quick, apparently WS has completed its beta testing.
3:06 pm
August 4, 2010
Offline
They've had it in beta for awhile now, although it never showed up for me. They have similar functionality - deposited in banks, 2.5% for all, CIPF instead of CIDC - in their managed income "Money Market Portfolio", with no actual management fee. This is available in all registration types, not just non-reg, and it isn't obvious if there are significant differences in this new savings account. I don't think it was always so, but moving money from the MMP to other accounts in your internal portfolio is instant now.
But by branding it separately from a "managed" account with a somewhat misleading MMP name, it will be easier to find and promote. They may have other differences now that is rolled out - eligibility or not for margin/line of credit, or something like that.
They also have their old "registered savings accounts", which are like the Chequing account without all the transactional stuff - tiered rates 1.25%/1.75%/2.25% based on client status (no direct deposit bump), CDIC (max $100K) etc.
12:25 pm
June 22, 2023
Offline
Northern Raven (are you as far north as Old Crow??!!) My (not literally mine) crows are getting ready to fly the coop for the winter soon. Very sad really!!:
So if I have a few thousand dollars of surplus cash in my RRSP, I would have to open a new RRSP MMP account and then transfer the cash from my trading RRSP to my RRSP MMP account which is now done in real time. When I find something that I want to invest in then I simply transfer the cash from my RRSP MMP to my trading RRSP.
If the above is accurate, why would they make this so clumsy, and not just create an ETF or MF to do it within my trading account. WS seems to like creating accounts, as if the senior managers have it as a bonus metric.
Anyways thanks for sharing this.
WS seems to realize that their customers like lotteries as their Monthly Millionaires contest has seemingly been an overwhelming marketing success.
9:00 pm
August 4, 2010
Offline
I spent over half my life North of 60, although I never lived quite as far north as Old Crow (over 67°N). I've travelled a bit further north, to Inuvik, and I think actually a touch more northerly on vacation in Norway. But my regret is missing out on a work trip many years ago which would have taken me to some combination of Pond Inlet/Resolute/Grise Fiord, which are 72°-76°N.
Wealthsimple isn't a creator of ETFs and MFs - their Shariah branded ETF and I think a couple of others were created in a partnership with Mackenzie Investments, which I think is part of the same Power Corp octopus. They have no need for all the paperwork and externalities of an actual fund, this stuff is just entries on their internal bookkeeping.
I tend to keep some cash in an MMF (I use Purpose's MNY) for my minimal trading needs, since that is also eligible for my small "just in case" portfolio LOC overdraft, where Savings or MMP are not. The yield (MNY is currently around 2.34%) is close enough to not worry about. I do have an MMP, and have opened a Savings now to probably replace it, but unless I have a known use for medium term cash upcoming, I tend to ship it over to a Hubert quarterly GIC (currently a blended 3.55%).
I notice the new Savings doesn't have the MMP wording that the funds are deposited with Canadian banks, which the MMP portfolios have. Both are covered by CIPF, but presumably the non-reg Savings is just a liability on their books, rather than the actual cash being in an actual WS bank account somewhere.
They could just pay the 2.5% on balances in trading accounts instead of the MMP, but that would probably sacrifice a lot of free float they are getting now from inertia and transfer nuisance. It may be banked anyway, but rather than pass along 2.5% of whatever bank interest the MMP is earning, they may be taking the responsibility for generating part of the return themselves (savings on more expensive wholesale funding or credit lines from their banks, or whatever).
2:37 am
June 22, 2023
Offline
By vehicle the farthest north in Canada that I have been is the top of the Top of the World highway. However, I spent less than half a day in Prudhoe Bay, Alaska many moons ago. The flight from Anchorage was on a 737 that was a half cargo/half human cattle carrier with the humans in the tail section. The manager of the big 8 accounting firm that I worked for screwed up and didn't think we needed to attend the client's inventory count that had already occurred. I am guessing he was reeducated by the engagement partner. So, I grew the straw to attend the inventory count for the auditor's benefit (a first and only in my experience) even though I was not on the audit team per se. The client was not too happy as he had to accompany me from Anchorage as well. It was around Halloween, but pretty frosty and very windy in Prudhoe Bay by then. I was still pretty green back then as the Weatherford guys laughed at me when they drove us to lunch and I informed them that the engine of the truck was still running (they leave them running 24/7 during cold season). The audit manager was an Irishman and as demonstrated above was never confused as a technocrat in the office, but he excelled as a schmoozer and much to my shock he became a partner eventually. The flight from Anchorage to Seattle was memorable for me as it was on my favorite civilian aircraft, an L-1011. The flight was nearly empty and I slept on the centre seats all the way back to Seattle. Had to wait until morning to get the flight home.
Like you the farthest north in Europe that I have been is in Scandinavia, specifically being Umea, Sweden. You strike me as being a strong technocrat (although you might very well be a schmoozer as well, although I have not encountered too many folks that excel at both). My Big 8 firm had an amazing tax asset, let's call him Eugene (affectionately known as Eugenius in the office). He was the ultimate technocrat, artificial intelligence before it's time. He was eventually shown the door as in the "brilliance" of the day someone thought that all partners should spend x% of their time doing marketing, no exceptions. Eugene was an exception or maybe just exceptional, but had no acumen, whatsoever for marketing. Hard to believe you nuke your intellectual property, because he has no chance of meeting the new marketing metric.
Thanks for sharing your insights into WS. I opened a Registered Savings Account on Friday.
7:57 am
August 4, 2010
Offline
Yes, those 737-200 "combi" flights with the cargo bulkhead are unique to the north, they got waivers from Transport Canada since you aren't allowed to do that in the south. The 737-200 conversions are pretty rare now, but I read that one of the northern airlines got the first 737-800 combi mod awhile back.
The L1011 looked nifty, but it became my least favourite jet when as a kid I sat for three hours in hot L1011s as two separate planes had minor glitches and Air Canada finally put us on something else to get us off the ground.
I was in Fairbanks, Alaska for an athletic competition in high school, but nowhere else in Alaska except Hyder, the little town encapsulated by BC near Stewart. In Scandinavia I went up the Norwegian coast to north of Narvik on the daily boats, and took the sleeper train across the north of Sweden into Finland and down to Helsinki.
We now return you to your regularly scheduled Weathsimple chat.
9:48 am
November 18, 2017
Offline
Off-topic warning:
Ah, the L-1011, my favourite plane!
RetirEd
5:10 pm
October 27, 2013
 Online
With a yield of 2.5%, should this new WS savings account not make it on to the HISA list, perhaps replacing the Chequing entry that is now there? With a caveat (footnote) that it is covered by CIPF insurance, not CDIC et al.
5:34 pm
January 12, 2019
Offline
- What AltaRed said ⬆️
Dean
 " Live Long, Healthy ... And Prosper ! "
6:23 pm
April 21, 2022
Offline
What Dean said ⬆️
Johnny
8:58 am
May 15, 2007
Offline
Yes, I should swap that in, and also add Haventree.
6:31 am
March 30, 2017
Offline
So the generation chequing account earns 2.25% and CDIC protected. This new savings account 2.5% is CIPF protected. A gain of 0.25% vs chequing account but not CDIC the only diff ?
12:21 pm
August 27, 2026
Offline
savemoresaveoften said
So the generation chequing account earns 2.25% and CDIC protected. This new savings account 2.5% is CIPF protected. A gain of 0.25% vs chequing account but not CDIC the only diff ?
The highest CDIC savings account on the chart seems to be Oaken at 2.8%.
Is a savings account backed by CIPF riskier than one backed by CDIC? Since they're paying less than 2.8%, if it were riskier, seems like the rate would have to be higher to compensate.
1:28 pm
April 27, 2017
Online
Freedom said
The highest CDIC savings account on the chart seems to be Oaken at 2.8%.
Is a savings account backed by CIPF riskier than one backed by CDIC? Since they're paying less than 2.8%, if it were riskier, seems like the rate would have to be higher to compensate.
There are other factors, like convenience. Wealthsimple does pretty much everything now, and much of it is done better than competing FIs. One-stop shop. Oaken is just a savings platform. If you don’t expect to touch the money frequently and it's under $100K then Oaken has advantages. Also, these rates are variable so things could change.
1:39 pm
November 8, 2018
Offline
Freedom said
Is a savings account backed by CIPF riskier than one backed by CDIC?
Depends how one defines risk. The government will never run out of money (they'll print more if needed), so CDIC coverage is ironclad within defined limits for different types of deposits.
CIPF has limited fund. From what I can find, it is about $600 million in cash. Someone please correct me if I am wrong.
Half a billion sounds huge, but CIPF offers coverage of up to $1M (or even more?). Simple math says CIPF fund is only enough to cover 600 people each having $1M deposited.
Now, how realistic is it for a CIPF member (or multiple at the same time) to fold and have more than $600M in CIPF covered deposits? That's the answer a person must give to themselves when calculating the risk.
For me personally, I am staying with CDIC. My cash deposits follow HISA chart from this Web site: I sort chart by rates from top rate to bottom, and my funds go to top entities from that list which are CDIC covered.
9:14 am
August 27, 2026
Offline
Case Insolvency Still on CIPF's books at Dec 31, 2015 Elapsed time
MF Global Canada 2011 $486,000 4+ years
Barret Capital Feb 2012 $8,000 3+ years
First Leaside Feb 2012 $1,379,000 3+ years
Octagon Capital 2015 $1,063,000 Under 1 year
this is a list of how long it took the CIPF to pay out to people
9:37 am
August 20, 2019
Offline
Google ai, gave me “a short, forum-ready reply you can copy and paste:
That's not actually what those numbers mean.
Those dollar figures are just residual funds left on CIPF's balance sheets for things like ongoing bankruptcy lawsuits, complex appeals on weird products, or unclaimed property where they couldn't find the account holder.
The vast majority of regular, everyday investors in those cases had their accounts transferred or paid out within the standard timeframe shortly after the collapse. It didn't take 4 years to pay regular people.”
Ok?
